
Unit Economics Analysis: A Practical Founder's Guide
What if a strong LTV:CAC ratio is hiding a business that struggles to grow profitably? Unit economics analysis for startups is more than calculating one ratio. The result depends on what you count as a unit, which costs you include, and how well your assumptions reflect the customer experience.
If you’re unsure whether to measure economics per customer, transaction, or product, you’re not alone. Acquisition costs can look deceptively low when salaries and overhead are left out, while revenue alone can make customer lifetime value seem healthier than it is. LTV, CAC, gross margin, and payback only become useful when you define them consistently and consider them together.
This guide will help you choose a unit that fits your business model, build a transparent analysis from relevant revenue and cost assumptions, and use the findings to make steadier growth decisions. We’ll work through the core calculations, show how to interpret the results in context, and connect them to practical choices about acquisition, retention, and operations. The goal isn’t a perfect ratio. It’s a clearer view of what makes growth durable.
Key Takeaways
- Choose a unit that reflects how your startup creates, delivers, and captures value, rather than defaulting to a convenient metric.
- Build unit economics analysis for startups from clearly defined revenue and relevant variable costs, with assumptions and cost boundaries made visible.
- Compare customer or product segments to reveal differences a blended average can conceal.
- Use a repeatable workflow to document data sources, time periods, and assumptions alongside each calculation.
- Turn the findings into focused questions about acquisition, pricing, retention, delivery, and capacity, then weigh the trade-offs before deciding how to grow.
What unit economics analysis means for a startup’s business model
Unit economics examines the revenue and costs associated with a meaningful unit of a business. The unit might be one customer, one transaction, one product sold, or one subscription account. The purpose of unit economics analysis for startups is to understand how value is created and what it takes to deliver it, not to force every business into the same calculation.
Choose a unit that follows the way your startup operates. Ask how customers pay, what triggers costs, and where the business expects value to accumulate. A unit that’s easy to count but disconnected from those mechanics can produce a tidy calculation that offers little guidance. For a foundation, consider the related idea of unit cost, or the cost associated with producing or providing one unit of output.
What counts as a unit in a startup?
A customer can be the most useful unit when the model depends on acquiring and retaining people or organizations over time. This view connects the initial cost of winning a customer with the revenue and service costs that follow. It’s especially relevant when repeat purchases, ongoing usage, or renewals shape the relationship. Define whether you’re measuring a new customer, an active customer, or a customer over a set period, since those choices change the calculation.
For businesses where value and costs accrue with each sale, a transaction or product may be more revealing. A marketplace might examine each completed transaction, while a seller could assess the economics of an individual product. If costs vary by order size, fulfillment method, or product type, compare those differences rather than relying on a single average.
For a recurring model, a subscription account may capture the relationship more clearly than an individual user, especially if organizations pay for multiple seats. The best unit depends on how the startup creates, delivers, and captures value. Some companies use a primary unit for core analysis and supporting units to understand important variations, such as differences in account size or service usage.
Why founders use unit economics analysis
A per-unit view makes the underlying revenue and cost relationships easier to inspect. Instead of looking only at total sales or spending, founders can ask what the business earns from a defined relationship or sale and which costs are directly connected to it. That focus can reveal assumptions to investigate, such as whether customer support, fulfillment, or discounts change as activity grows.
Unit economics show what a business earns and spends to create and serve one meaningful unit of value. That perspective can inform decisions about pricing, acquisition, retention, and operating priorities. It doesn’t replace the full view: a favorable result per customer, for example, doesn’t account by itself for fixed costs, cash needs, or whether the company has the capacity to serve more customers. Use unit-level findings alongside overall performance to make decisions with clearer context.
How to calculate startup unit economics without hiding costs
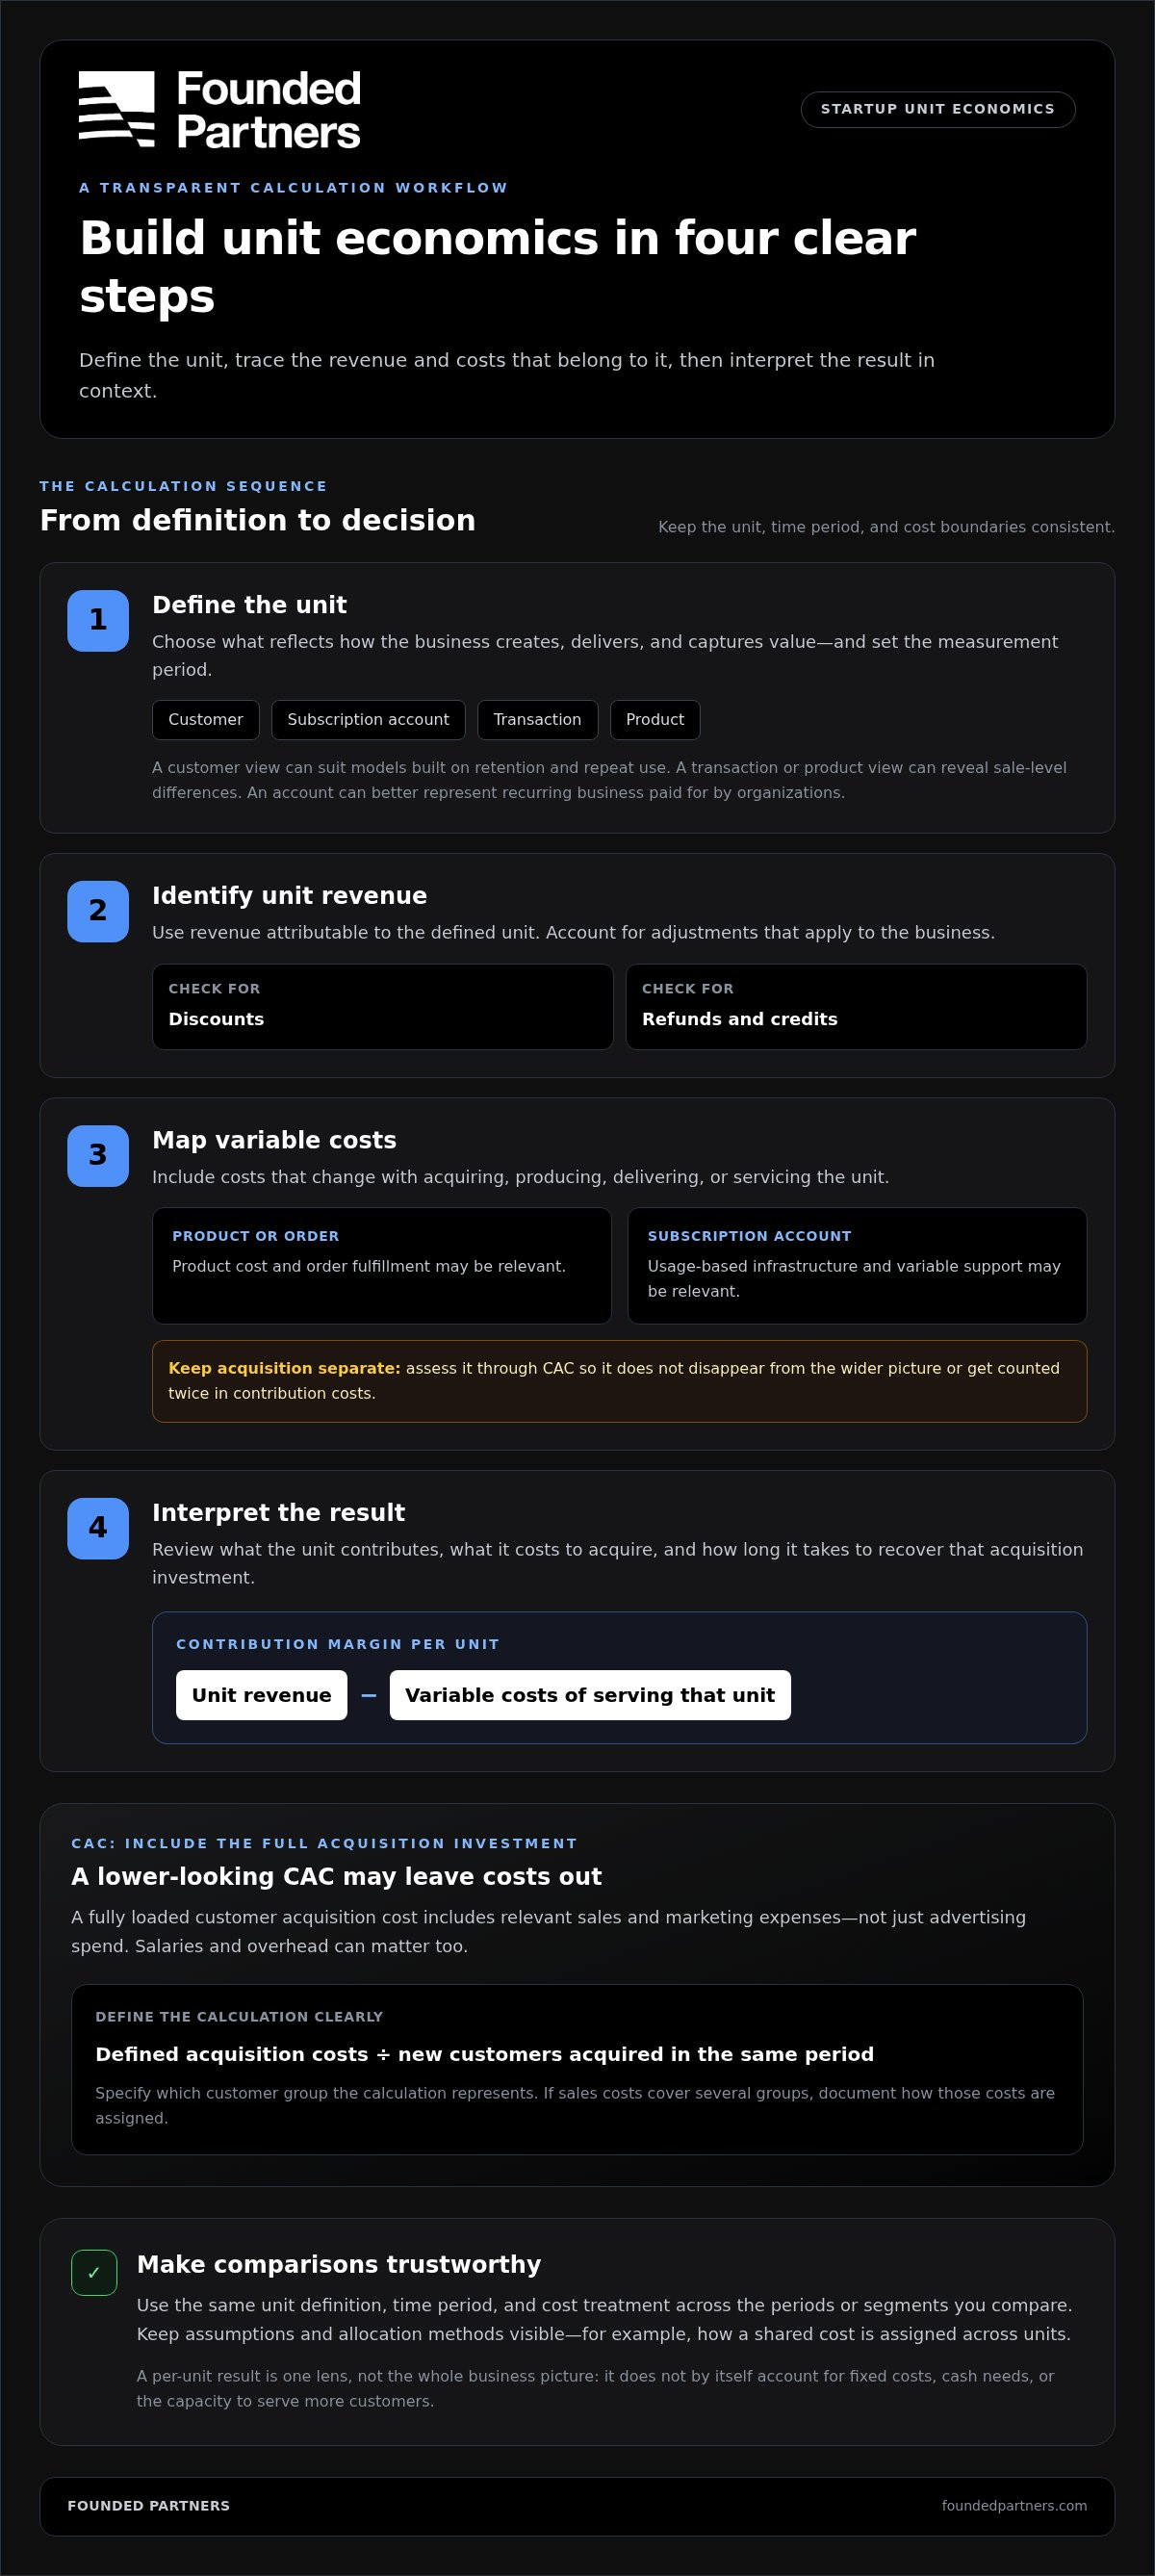
A useful calculation is built in sequence, not assembled from whichever numbers are easiest to find. First define the unit, then identify the revenue attributable to it, map the direct costs of acquiring and serving it, and interpret what remains. In unit economics analysis for startups, consistency matters: the unit, time period, and cost boundaries need to mean the same thing across the periods or segments you compare.
- Define the unit. Decide whether you’re analyzing a customer, account, transaction, or product, and set the time period.
- Identify unit revenue. Use revenue attributable to that unit, accounting for discounts, refunds, credits, or other adjustments relevant to the business.
- Map variable costs. Include costs that change with acquiring, producing, delivering, or servicing the unit.
- Interpret the result. Review what the unit contributes, what it costs to acquire, and how long it takes to recover that acquisition investment.
Calculate unit revenue and contribution margin
Contribution margin per unit = unit revenue − variable costs of serving that unit. For a product sale, relevant costs might include the product and order fulfillment. For a subscription account, they might include usage-based infrastructure and support that varies with service. Include acquisition expense separately when assessing CAC, so it doesn’t disappear from the wider picture or get counted twice in contribution costs.
Keep assumptions visible. If discounts are deducted from revenue in one period, treat them consistently in the next; if a cost is allocated across units, document the basis. Check that the measurement period, unit definition, and cost treatment are comparable before interpreting a change as improved or weakened performance.
Relate CAC, LTV, and payback to the unit
Customer acquisition cost (CAC) is the acquisition investment associated with gaining a customer or account. A fully loaded view includes relevant sales and marketing expenses, such as salaries and overhead, not just advertising spend. Divide the defined acquisition costs by the number of new customers acquired in the same period, and be clear about which customer group the calculation represents. If sales costs cover several customer groups, document how you assign them.
Lifetime value (LTV) estimates the value a customer may generate over the relationship. It depends on revenue, gross margin, retention, and the assumptions used to forecast future behavior. Payback asks how long it takes for the contribution generated by that customer to recover the acquisition investment. These measures belong together, but there’s no universal target ratio that makes sense for every model or stage.
Separate unit-level variable costs from broader fixed or company-wide expenses, such as general administration or facilities. Don’t assign the same expense to a unit and then include it again in a separate company-wide calculation. Keep a clear record of what the unit calculation covers, then review the wider financial picture alongside it.
Calculation quality depends on consistent definitions of the unit, revenue, and costs. Founders can use the result to frame consequential choices about growth and operations. Collaborative founder advisory can help connect those findings to broader business priorities.
How to interpret startup unit economics across customers and growth stages
A blended average can smooth over the differences founders need to see. Customers acquired through different channels may have different retention patterns; products may carry different delivery costs; and an account that uses more support may contribute differently from one that needs little assistance. Unit economics analysis for startups becomes more useful when you compare like with like and keep the underlying assumptions visible.
A positive contribution margin or promising customer metric is not proof that the whole company is profitable. Company-wide expenses, cash timing, and the costs of building capacity still matter. Read unit-level signals alongside the broader financial picture, and ask whether the result holds across relevant customer groups and periods.
Compare cohorts and customer segments carefully
A cohort is a group of customers that shares a starting point, often the period in which they were acquired. Comparing cohorts over the same span can show whether retention, spending, or servicing needs vary by acquisition channel or customer type. For example, customers gained through a referral channel may behave differently from those acquired through paid campaigns. Compare equivalent periods and treat early patterns as evidence to examine, not a guarantee that future customers will behave the same way.
| Unit | Segment to compare | Cost assumptions to examine | Interpretation question |
|---|---|---|---|
| Customer | Acquisition channel or customer type | Acquisition effort, onboarding, ongoing support | Do retention and servicing needs differ across groups? |
| Transaction | Order size or sales channel | Payment processing, fulfillment, discounts | Does each sale contribute similarly after variable costs? |
| Product | Product line or usage profile | Production, delivery, and usage-related costs | Which products create different cost-to-serve patterns? |
| Subscription account | Plan type or account size | Service usage, support, and onboarding | Does recurring revenue align with the resources each account uses? |
Read ratios and payback in context
LTV/CAC compares estimated customer value with the cost of acquisition. It can indicate whether the expected value of a customer appears proportionate to the investment required to acquire them. But both sides are estimates: LTV depends on assumptions about revenue, margin, and retention, while CAC depends on which acquisition expenses and customer groups are included. A ratio can look strong because of optimistic assumptions or an incomplete cost boundary.
Payback adds a timing perspective. It asks how long contribution from a customer takes to recover the acquisition investment. That timing matters because a startup must fund costs before that investment is recovered. A customer relationship may look attractive over its forecast lifetime and still place pressure on cash if recovery takes longer than the business can comfortably support.
A benchmark is context, not a substitute for analysis. Published comparisons can offer orientation, but they may reflect a different business model, stage, customer mix, or calculation method. Use them to frame questions, then prioritize consistent definitions, transparent assumptions, and comparisons across your own relevant segments and periods.
A practical unit economics analysis workflow for startup founders
A repeatable process makes your analysis easier to check, update, and use in decisions. Treat it as a working model, not a one-time answer. In unit economics analysis for startups, the discipline lies in making each choice visible, from the question you’re asking to the boundaries of the costs you include.
- Define the question. Be specific about the decision the analysis should inform. Are you assessing a channel, comparing customer types, or examining whether a change in delivery affects contribution?
- Choose the unit. Select the customer, account, transaction, or product that best matches the question. Keep the unit consistent with the value and costs you intend to examine.
- Gather the inputs. Pull revenue and cost data from operating and financial records. Record each source, the time period it covers, and any adjustments or exclusions.
- Calculate the result. Apply the same definitions across relevant periods and segments. Separate observed figures from estimates so uncertainty doesn’t get hidden inside a single output.
- Review and investigate. Compare the result with prior periods and operating records. Follow up on material changes rather than smoothing them away or assuming they are temporary.
Build a clear, auditable analysis
Put the calculation and its assumptions side by side. Note the unit, date range, data sources, cost boundaries, and any estimates. If a revenue item or cost is excluded, state why. This lets another person understand how the result was formed and helps distinguish a change in business performance from a change in measurement.
Consistency is essential for comparison. If you change how support costs are allocated, show where the new method begins rather than treating the revised figures as directly comparable without explanation. Check calculated values against records such as sales, customer, and service data. When the numbers diverge, investigate the difference before drawing a conclusion.
A sound unit view also sits within the wider operating model. As a startup considers whether its processes and capacity can support growth, a business scalability consulting guide can help frame questions about sustainable operating foundations.
Review changes and turn findings into questions
When a result shifts, look for what changed before deciding what it means. Did acquisition patterns move? Did customers renew or purchase differently? Did pricing, discounts, or delivery effort change? Check which assumptions have the greatest influence on the calculation, then test how a reasonable change to those assumptions affects your interpretation. This makes uncertainty easier to discuss and reduces the risk of treating a forecast as a fact.
Use the analysis to sharpen the next decision, not to automate it. If growth plans depend on new investment, connect the operating evidence to the broader funding case. Founders weighing that step can explore capital raising for founders as part of the wider growth discussion.
For consequential choices, work with Founded Partners on founder advisory to connect unit-level findings with broader growth and operating priorities.
Turn unit economics insights into stronger startup growth decisions
A unit-level result is a signal for a decision, not an instruction to scale, cut spending, or change prices. Use it to frame the next questions: Is acquisition bringing in customers who stay? Does pricing reflect the cost of delivering value? Can the team support more volume without compromising service or adding costs that change the economics?
Look across the operating model before acting. A weak result might point to acquisition costs, but it could also reflect onboarding effort, product usage, delivery processes, or a customer segment that needs more support. A strong result can also have limits if the company lacks the people, systems, or cash capacity to serve increased demand. Unit economics analysis for startups helps founders make these trade-offs visible, while judgment and wider business context shape the choice.
Use the analysis to frame growth and capital conversations
Transparent assumptions help founders explain why a growth decision makes sense, what could change the result, and what they’ll monitor next. For example, a decision to invest in a new acquisition channel should consider not only its expected customer economics but also how those customers retain and what it takes to serve them. The analysis can strengthen a strategic discussion, but it can’t guarantee a financing outcome or substitute for a complete view of the business.
As operating changes are made, define how you’ll assess whether they’re working. Pair unit-level measures with relevant operating indicators, then compare outcomes against the original assumptions. This creates a grounded way to assess transformation and distinguish a lasting improvement from a short-term shift.
If the findings inform a broader growth plan, they can also contribute to a clear capital conversation. Founders considering that connection can explore capital raising for founders as part of their strategic planning, while keeping the unit-level evidence distinct from the wider case for investment.
When experienced founder advisory can help
Some decisions require more than a spreadsheet. Founders may need to weigh unit economics against leadership capacity, operational priorities, or a shift in growth strategy. Founded Partners’ one-on-one Founder Advisory, provided by Co-Founder and Chief Advisor Adam Miron, offers hands-on support for working through consequential business choices. Strategic Growth & Business Transformation, led by Matt Pierce, connects those choices to broader business foundations and change.
Founded Partners’ company-wide experience includes founding 25+ companies, supporting 100+ acquisitions and 35+ acquisitions, and advising companies with $3B+ in market cap created. These figures describe the firm’s overall experience, not the results of a particular advisory service. The value of unit economics is in making assumptions and trade-offs clearer, then using that clarity to guide considered action.
Let’s talk about the decisions shaping your company’s next stage.
Make the next growth decision with greater clarity
The value of unit economics analysis for startups grows when it becomes part of how you make decisions, not a model you revisit only when a major question arises. Choose a clear signal that would prompt a review, decide who will monitor it, and agree on what evidence would support changing course. That creates a steadier link between the assumptions behind a plan and what the business experiences as it develops.
Some decisions reach beyond a single metric. A shift in growth priorities can affect leadership, operations, and the organization’s readiness for change. Founded Partners’ seasoned leaders bring experience guiding organizations through growth, exits, and complex challenges, helping founders consider how strategic choices connect across the business.
You don’t need certainty about every future outcome to take a thoughtful next step. You need a clear view of the decision in front of you and a willingness to learn as conditions change. Let’s talk with Founded Partners about your growth priorities and the choices shaping your next stage.
Frequently Asked Questions
Does positive unit economics mean a startup is profitable?
No. Positive unit economics means a defined unit generates more revenue than the costs included in that particular calculation. The company may still spend more on salaries, product development, rent, or other overhead than it earns overall. For example, each order could contribute toward overhead while total orders remain too low to cover those broader expenses. Treat unit-level results as one input to a company-wide view, not as proof of profitability.
Can a startup analyze unit economics before it has extensive customer history?
Yes. Early analysis can use pilot sales, initial customer interviews, supplier quotes, and limited operating data to form a provisional view. Keep observed results separate from estimates, and identify which assumptions rely on small samples or expected behavior. A founder might model different renewal or usage scenarios rather than present one forecast as established fact. Update the analysis as actual customer activity accumulates, and note where new evidence changes the picture.
How should a marketplace define its unit for unit economics analysis?
A marketplace can examine an individual completed transaction, but should also consider the economics of the buyer and seller sides. One transaction may generate revenue while requiring separate costs to attract, verify, support, or retain each participant. For example, a marketplace might track transaction contribution alongside the cost of bringing an active seller onto the platform. This helps show whether growth is balanced across both sides, rather than hiding one side’s costs in an overall average.
Should fixed costs be included in a unit economics calculation?
Usually, keep fixed costs separate from a contribution calculation focused on costs that vary with each unit. Then compare total contribution with company-wide expenses to understand whether the business covers its operating base. If you allocate fixed costs across units for a fuller view, state the allocation method and apply it consistently. For instance, allocating a shared team’s time based on usage can support analysis, but avoid counting that same expense again elsewhere.
How do discounts and refunds affect unit economics?
Discounts reduce the revenue attributable to a sale, while refunds can reverse some or all of the revenue after a transaction. Include them in the period or cohort connected to the original activity, and make the treatment clear if refunds arrive later. For example, compare orders before and after a promotion using net revenue and the same cost boundaries. Otherwise, a higher sales count may appear to improve unit results even as discounting reduces what the business keeps.
Is LTV reliable for an early-stage startup?
It can be useful as a working estimate, but early-stage LTV is often sensitive to limited retention history and forecast assumptions. Avoid presenting a long customer lifetime as established evidence when the business has only observed a short relationship. Instead, show a cautious case based on known behavior and alternative cases that make different retention assumptions. This makes the uncertainty visible and gives the team a clear reason to revisit the estimate as customer history develops.